Second home loans in Mississippi
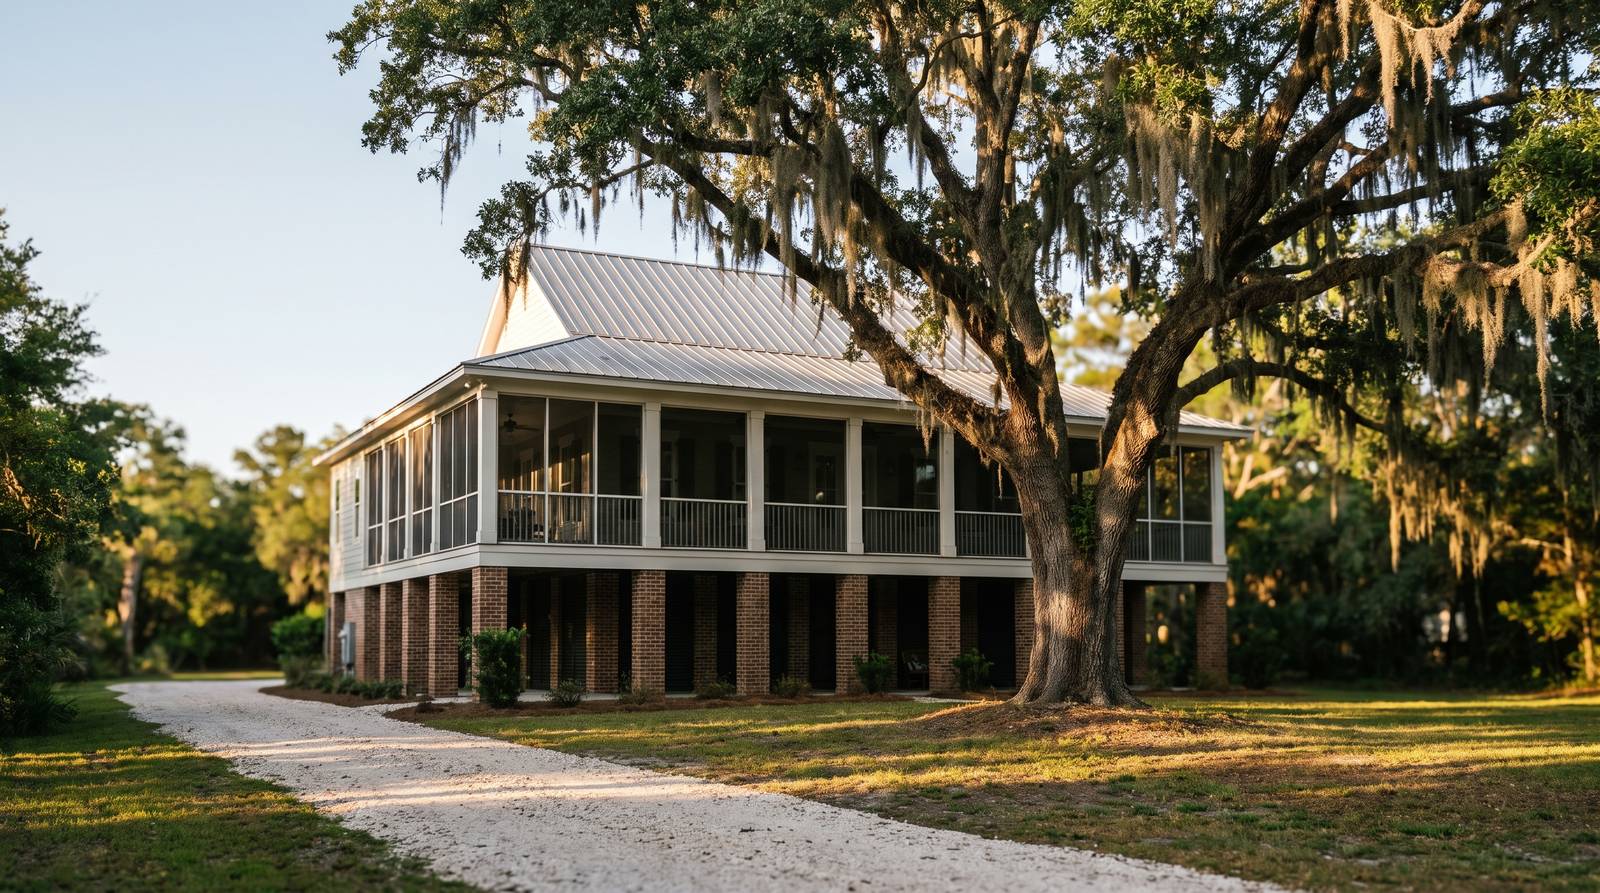
A coast that rebuilt itself elevated after 2005 and a set of quieter inland lakes. On the coast the height of the house and the cost of the wind policy tend to decide the file.
Where second home buying concentrates in Mississippi
Mississippi's second home demand sits in three areas that have very little to do with one another.
- Hancock and Harrison counties, meaning Bay St. Louis, Waveland, Pass Christian, Long Beach and Gulfport, the beach-front and near-beach market and the one most thoroughly rebuilt after 2005.
- Ocean Springs and coastal Jackson County, east of Biloxi, a quieter and more established version of the same coast with a stronger year-round population.
- The Barnett Reservoir, immediately northeast of Jackson, close enough to the metro that owners use it most weekends rather than seasonally.
- Sardis, Enid, Grenada and Arkabutla, the flood control lakes across north Mississippi, drawing weekend owners from Memphis and the Delta.
- Pickwick and Tishomingo County, in the northeast corner where Mississippi, Alabama and Tennessee meet, the state's only genuinely hilly water market.
- Oxford and the Ole Miss corridor, where second home demand is driven by football weekends and family use rather than by recreation, and where the occupancy question comes up in a different form.
Those are descriptions of where the market is, not a claim about prices or returns. The coast and the inland lakes raise almost entirely separate questions.
Source: U.S. Census Bureau, American Community Survey 5-year estimates, 2023, tables B25004 and B25001.
What usually decides a Mississippi file
On the coast, elevation is an underwriting fact
Much of the Mississippi beach front was rebuilt on piers after 2005, and a great deal of what is for sale now sits well above grade by design. That matters in three places at once. The flood zone and the finished floor elevation drive the flood premium, an elevation certificate is frequently what the insurer wants to see before quoting, and the appraiser needs comparable sales of similarly elevated construction, which in some stretches of Hancock County is a thinner pool than it looks.
None of this is a reason not to buy on the coast. It is a reason to get the elevation certificate and real insurance quotes during the inspection period rather than assuming the seller's numbers still apply.
The wind policy is usually separate, and it counts
Along the Mississippi coast a standard homeowners policy commonly excludes wind and hail, which is then written separately, with flood separate again. The state runs a residual market for the wind piece, the Mississippi Windstorm Underwriting Association, generally called the wind pool, which serves the coastal area covering George, Hancock, Harrison, Jackson, Pearl River and Stone counties and exists for owners who cannot get the coverage in the open market.
Source: Mississippi Windstorm Underwriting Association, About Us.
Why a lender cares: those premiums go into the monthly housing obligation used to calculate debt to income, alongside taxes and any association dues. A buyer who priced the purchase off the mortgage payment alone can find the file tightens at the last step. Quotes, not estimates, and early.
The rental question, in a state with two versions of it
On the coast the question is the familiar one. Fannie Mae's Selling Guide says a second home cannot be subject to any agreements that give a management firm control over the occupancy
and that the borrower must retain exclusive control of the property, so a unit that stays in a management company's program after closing is an investment property purchase rather than a second home.
Source: Fannie Mae Selling Guide B2-1.1-01, Occupancy Types.
Around Oxford it arrives differently, as a house bought for family use during the season that a relative also occupies, or that gets rented on football weekends. The test is the same in both places: how the property will actually be used, and what agreements it is subject to. The terms follow from the answer. The Fannie Mae Eligibility Matrix, August 2026 edition, lists 90% as the maximum loan-to-value on a one-unit second home purchase against 85% on a one-unit investment property, with higher reserve expectations on the investment file.
Source: Fannie Mae Selling Guide, Eligibility.
Inland, the questions are ordinary and the stock is older
On the north Mississippi lakes and around the Barnett Reservoir the file looks like any other lake purchase. A second home has to be suitable for year-round occupancy, and the older cottage stock includes seasonal construction, additions done without permits, private drives and shared or aging septic systems. Those are appraisal and inspection items. Where a dock or shoreline structure exists, whether it is permitted and whether the permit transfers is worth confirming in writing during the inspection period rather than at closing.
Manufactured and modular construction
Mississippi has a larger share of manufactured housing than most states, and it turns up in both the lake markets and the coastal ones. Financing is available, but the eligibility rules for a manufactured home are their own set, distinct from site-built construction, and they interact with the second home occupancy rules. It is worth establishing what the property actually is before an offer, because the answer changes the loan rather than adjusting it.
Which guides matter most here
For a Mississippi purchase, these three carry most of the weight.
Licensing in Mississippi
Residential Mortgage, LLC is authorized to close loans in Mississippi, one of the 27 states on the company's published authorization list. Bryan Piccolomini holds NMLS #228509 and Residential Mortgage, LLC holds NMLS #167729. Both can be checked independently on NMLS Consumer Access. Fuller detail is on the licensing page.
Common questions
Can Bryan lend on a second home in Mississippi?
Yes. Residential Mortgage, LLC is authorized to close loans in Mississippi, one of the 27 states on the company's published authorization list, and Bryan Piccolomini holds NMLS #228509.
Why does everyone ask about elevation on the coast?
Because it changes three things at once. The finished floor elevation and the flood zone drive the flood premium, insurers frequently want an elevation certificate before they will quote, and the appraiser needs comparable sales of similarly elevated construction. It is worth having the certificate in hand during the inspection period.
Is wind coverage really a separate policy?
On the Mississippi coast it commonly is. A standard homeowners policy frequently excludes wind and hail, and flood is separate again. Mississippi runs a residual market for the wind peril covering the six coastal counties, for owners who cannot obtain the coverage in the open market. All of those premiums count toward the monthly obligation a lender uses.
Can I rent the house out on football weekends?
That depends on what you sign and how the property is actually used. A second home cannot be subject to an agreement that gives a management firm control over the occupancy, and you have to retain exclusive control. Occasional personal-arrangement use is a different thing from enrollment in a rental program, and the distinction is worth settling before the offer rather than after.
Does a manufactured home qualify as a second home?
It can, but manufactured housing carries its own eligibility rules, separate from site-built construction, and they sit on top of the second home occupancy rules. Establish what the property is before an offer goes in, because the answer changes the loan rather than adjusting it.
More states: all 27. Run the arithmetic first on the calculators page.
Price the insurance before you price the payment
On the Mississippi coast, the wind and flood policies decide whether the file works as easily as the loan amount does.